Collision Coverage on a Luxury Car
Collision coverage pays to repair or replace your luxury car after it hits another vehicle or object, or rolls over, no matter who caused it.
What collision coverage actually pays for
Covers
- Collision with another vehicle It pays toward repairs to your car regardless of who was at fault.
- Hitting a fixed object A mailbox, a guardrail, a garage door, any of these count as collision if your car hits it.
- Single car rollover If you lose control and roll the car without hitting anything else, this is still a collision claim.
- Potholes and road damage Damage from hitting a pothole or a piece of road debris falls under collision, not comprehensive.
- Total loss from a crash If the car is damaged beyond repair in a collision, this coverage pays out its value instead of fixing it.
Doesn't cover
- Hail or storm damage Weather damage to a parked car falls under comprehensive coverage instead.
- Theft of the vehicle A stolen car is a comprehensive claim, not a collision one.
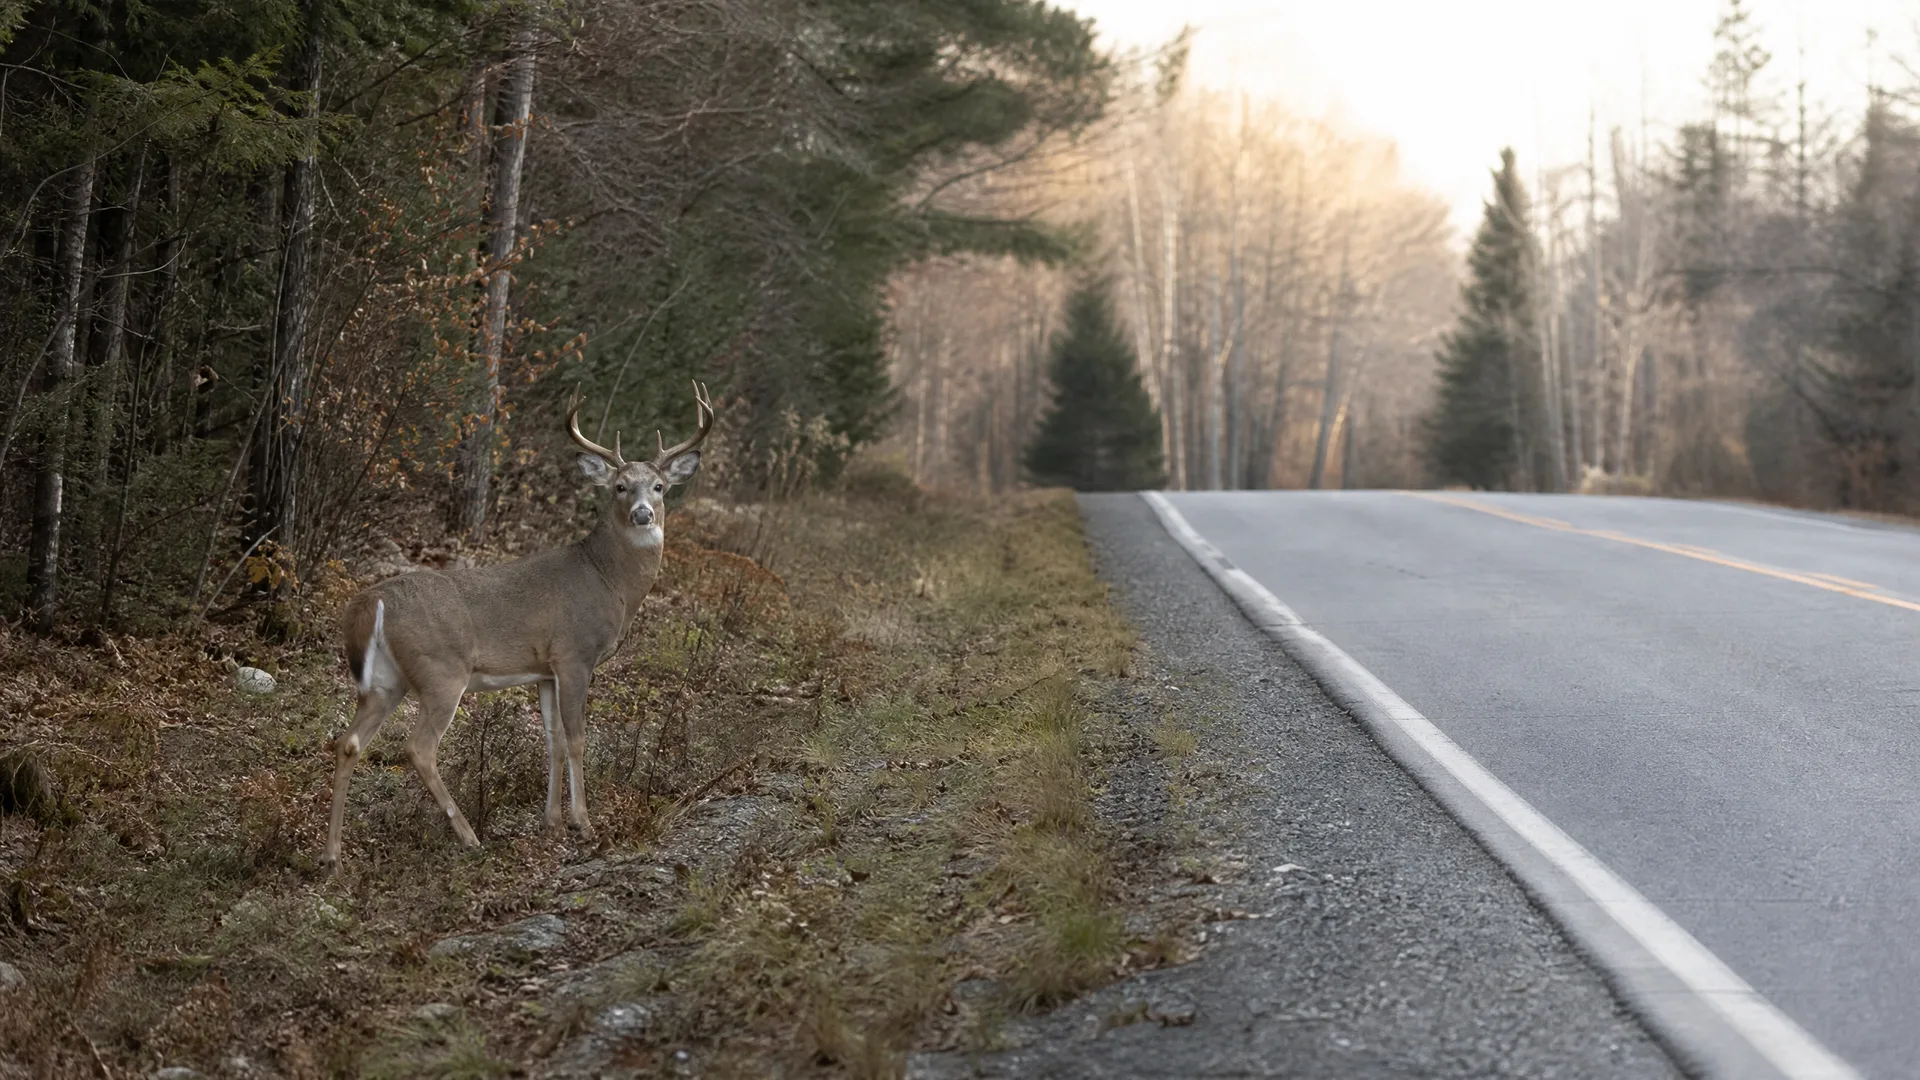
- Hitting a deer or animal Most insurers treat animal collisions as comprehensive claims even though a vehicle is involved.
- Mechanical breakdown A failed transmission or engine problem isn't a collision and isn't covered by either coverage.
- Injuries to you or others Medical costs are handled by medical payments, personal injury protection, or liability coverage, not this one.
Whether it's worth keeping depends on what the car is worth to you now, not what you paid
If the car is paid off and worth a meaningful amount, collision coverage protects real money you'd otherwise have to replace out of pocket. A luxury car often holds enough value for years that dropping this coverage early costs you more than it saves.
If you could write a check today to repair or replace the car without strain, carrying this coverage becomes more about convenience than necessity. Some drivers at this stage have the savings to self insure and would rather keep the premium.
How much you drive matters too. A car that mostly sits in the garage and makes short trips to church or the store carries less risk than one driven daily on the highway, and that changes the math on what you're paying for.
Where the car spends its nights counts as well. A locked garage versus street parking changes the odds of a collision claim, though it affects comprehensive risk more than this one. Still, it's worth factoring in alongside everything else.
How a collision claim actually works
You pay a deductible first, and the coverage pays the rest of the approved repair cost or the car's value if it's totaled. The deductible amount is something you chose when you set up the policy, and you can usually find it printed on your declarations page.
After a crash, you report the claim, an adjuster evaluates the damage, and the insurer either approves a repair shop estimate or declares the car a total loss based on its current value. For a luxury car, insurers sometimes require specific manufacturer parts or certified shops, so ask early what your policy allows.
The payout covers the physical damage to your car. It won't cover a rental car, towing, or the other driver's vehicle unless you have those coverages too. Have your policy number, photos of the damage, and a description of what happened ready when you call.
If the car is declared a total loss, the insurer pays its value at the time of the crash, not what you originally paid or what it would cost to replace with a new one. That number can surprise owners of cars that depreciate quickly.
Collision coverage versus comprehensive coverage
Collision coverage
This pays for damage from hitting another vehicle or object, or from a rollover. It applies regardless of fault and is usually required if you have a loan or lease.
Comprehensive coverage
This pays for damage from things other than a collision, like weather, theft, fire, or an animal running into your path. It's often paired with collision but covers a different set of risks.
If your car is paid off and you're deciding between the two, comprehensive is usually the one worth keeping longer since it covers risks you can't avoid by driving carefully.
Real situations
Your car is parked at church and a hailstorm rolls through while you're inside.
This doesn't pay because hail is a comprehensive claim, not a collision one.
A deer runs into the road at dusk on a county highway and you can't stop in time.
This doesn't pay either, since hitting an animal is typically treated as comprehensive.
You misjudge the distance backing out of a parking space and clip a concrete post.
This pays, since hitting a fixed object is a textbook collision claim.
Once you know whether you want to keep, adjust, or drop collision coverage on your car, you're ready to compare quotes built around that choice.
Questions people ask about this
What happens to collision coverage if I pay off my car loan?
Nothing happens automatically, since collision coverage stays on your policy until you remove it. Once a loan is paid off, the lender can no longer require it, so it becomes your choice whether to keep it based on the car's value and your savings.
Does collision coverage follow the car or the driver?
It generally follows the car, so anyone you've allowed to drive it is typically covered under your policy's collision coverage while driving it. Check your policy for any listed driver exclusions, since those can change this.
Can I add collision coverage back after dropping it?
Yes, you can usually add it back at your next renewal or by contacting your insurer directly. There may be a brief waiting period or a required photo inspection of the car's current condition before it takes effect.
Does collision coverage cost more for a luxury car?
Generally yes, since premiums are tied to how expensive the car is to repair or replace. Specialized parts and certified repair shops for luxury vehicles tend to push the cost higher than for an ordinary car.
What is my luxury car worth for insurance purposes?
It's worth whatever the insurer determines its current market value to be at the time of a claim, not what you paid or what it would cost new. You can get a rough sense of this by checking recent sale prices for similar cars with similar mileage and condition.


