Collision Coverage for Pothole Damage
Collision coverage pays to repair or replace your car when it hits something, and a pothole counts, so this is the coverage that handles the bent rim, blown tire, or cracked wheel from a bad stretch of road.
What this coverage pays for
Covers
- Wheel and rim damage A bent or cracked rim from dropping into a pothole is repaired or replaced under this coverage.
- Tire blowouts from impact If the pothole causes a tire to blow rather than just wear out, that's treated as collision damage.
- Suspension damage A hard hit can knock a strut, tie rod, or control arm out of alignment, and those repairs are covered.
- Undercarriage and frame damage Scraped or bent undercarriage parts from bottoming out are covered the same as any other collision damage.
- Towing after the damage disables the car If the pothole leaves you unable to drive, getting the car to a shop is handled as part of the claim.
Doesn't cover
- Routine tire wear A tire that's simply worn out isn't a collision claim, even if a pothole made it worse.
- Flat tires with no impact damage A slow leak or an old tire giving out isn't something this coverage pays for.
- Damage from a road you knew was bad Coverage doesn't change based on how the damage happened, but some policies ask about circumstances, so answer honestly.
- Mechanical breakdown unrelated to the pothole A part that fails on its own, like a worn bearing, falls under mechanical breakdown coverage if you carry it, not this.
- The cost below your deductible Small repairs that cost less than your deductible come out of your own pocket regardless of this coverage.
For most older drivers with a car that's paid off and worth keeping, this coverage is worth having
The decision mostly comes down to what the car is worth and whether you could cover a bad repair bill yourself without much strain. If the car is older and worth a modest amount, a wheel and suspension repair could easily come close to its value, and this coverage protects against that math working against you.
How much you drive matters too. Someone who still puts real miles on county roads or older highways, the kind with more patchwork and more potholes, faces this risk more often than someone who mostly drives short distances on well-kept streets. If your car mostly sits in the garage, the odds of needing this coverage drop.
Where the car is kept overnight matters less for this particular risk than it does for theft or weather coverage, since potholes are a driving hazard, not a parking hazard. What matters more is your daily route and how rough it tends to be.
If you could pay for a wheel or suspension repair out of savings without it changing anything, and the car itself isn't worth much, you may decide the premium isn't earning its keep. That's a reasonable call to make once you've looked at the actual numbers on your policy, not a sign you're taking on risk you can't handle.
How a pothole claim actually goes
You pay your deductible first, and the coverage picks up the rest of the repair cost up to what the car is worth. If the damage is minor, the repair bill may land close to or even under your deductible, in which case there's no real benefit to filing a claim at all.
To file, you'll want the date and rough location of the pothole, photos of the damage if you can get them, and a repair estimate from a shop. An adjuster will look at the damage and confirm it matches a collision event rather than ordinary wear, which is why tire wear and old suspension problems can get questioned.
The payout covers the repair or the car's value if it's totaled, not a rental car or your time, unless you carry separate coverage for those. Keep any receipts and the shop's written estimate, since those are what the claim is built around.
Collision coverage vs comprehensive coverage
Collision coverage
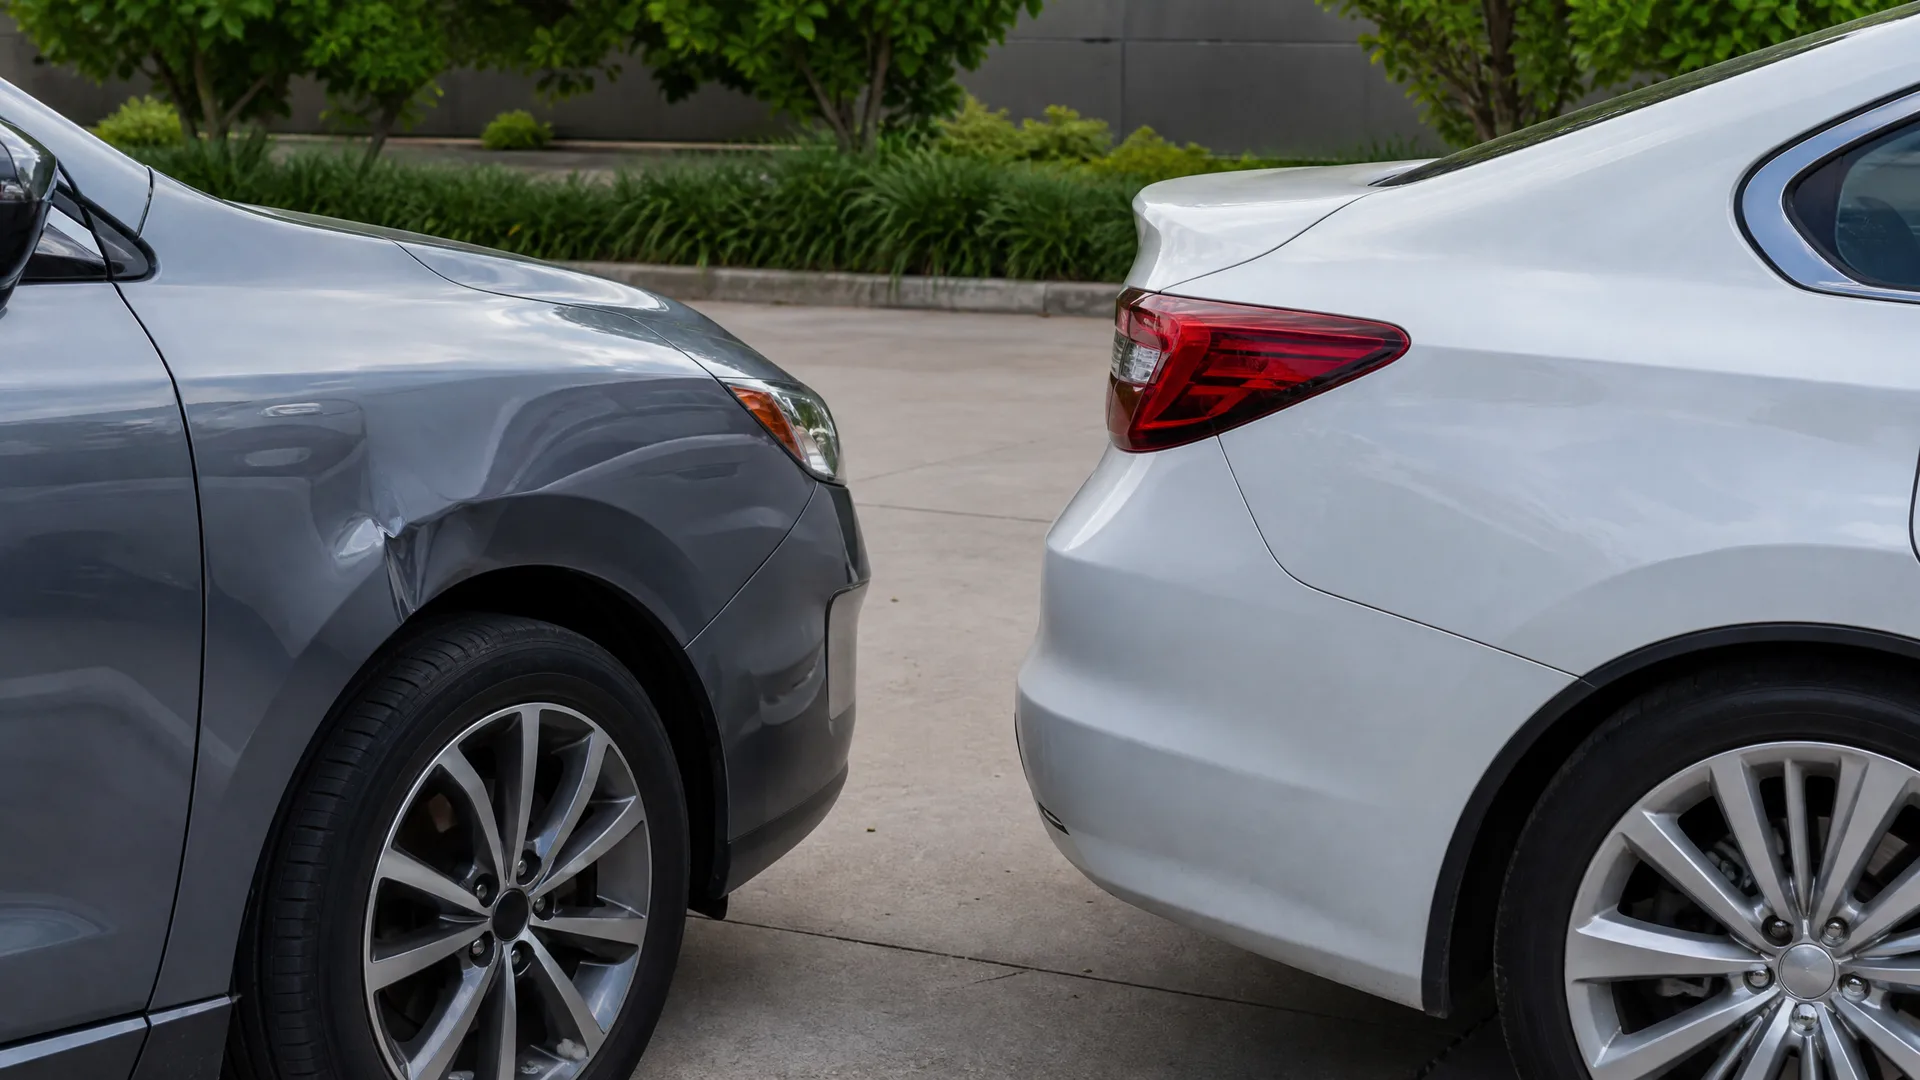
This pays for damage from hitting something, whether that's a pothole, a curb, another car, or a stationary object. It applies regardless of who's at fault.
Comprehensive coverage
This pays for damage that isn't from a collision, like hail, a falling tree branch, a cracked windshield from a rock, or an animal strike. It's a separate line with its own deductible.
If the damage comes from hitting the road itself, like a pothole, lean on collision, and keep comprehensive for the damage that happens without any impact with the road.
Real situations
You hit a deep pothole on a back road at dusk and the rim bends badly enough that the tire won't hold air.
This pays, since the damage came from an impact with the road.
A hailstorm hits while your car is parked at church and dents the hood and roof.
This doesn't pay, since there's no impact with the road. That falls under comprehensive coverage instead.
You swerve to avoid a pothole and clip a curb, damaging the wheel and the side mirror.
This pays, since curb impact is treated the same as any other collision damage.
Once you know whether you want this coverage, and at what deductible, you're ready to compare quotes with that decision already settled.
Questions people ask about this
Does a pothole claim count against me like an accident would?
It can affect your claims history even though no other driver was involved, since it's still a collision claim. How much it affects your rate varies by insurer and by how many claims you've filed recently, so it's worth asking your agent directly how your policy treats it.
Can I get reimbursed for pothole damage without filing an insurance claim?
Sometimes, if the road is a state or local highway and the agency has a claims process for road damage, but this depends entirely on your state and local government, not your insurance policy. It's usually a separate, slower process, and most people only pursue it for larger repair bills.
Does raising my deductible make sense if I mostly drive on well maintained roads?
It can, since a higher deductible lowers what you pay for the coverage and you're accepting more of the small repair costs yourself. This only makes sense if you're confident you could cover that deductible amount without strain, and if your driving really does keep you off rougher roads most of the time.
What happens if the pothole damage is severe enough to total the car?
The coverage pays out the car's value at the time of the damage, not what you originally paid for it. For an older car that's been paid off for years, that value may be lower than you expect, which is worth checking against what a replacement would actually cost.
Should I drop collision coverage once my car loan is paid off?
Not automatically, since the loan has nothing to do with whether the coverage still makes sense for you. The better question is whether the car's current value and your ability to cover a bad repair from savings still justify the premium, which is the same question regardless of whether you owe money on it.


